By Rob Dietrich | REALTOR® | eXp Realty Georgia
Well, here's one for the books.
I recently got fired by a prospective real estate investor.
And here's the funny part.
We hadn't even signed a buyer brokerage agreement! 😂
Now, does that sting a little? Of course it does. I'm human.
But after reflecting on the experience, I'm beginning to think I may have saved myself a considerable amount of time.
More importantly, the whole experience highlighted something every real estate investor should understand:
It's not necessarily what you buy that determines your investment success. It's what your money actually earns, and the risk you take to earn it.
Let me explain.
This Wasn't Your Typical Property Search
I was working with a prospective investor interested in income-producing real estate, with a budget of up to $1 million.
Rather than simply emailing MLS listings, I wanted to provide something considerably more useful.
So I built the investor a personalized real estate investment website.
Not a generic search portal. Their own private investment research platform.
The website featured:
- Carefully selected investment opportunities.
- An interactive map displaying property locations.
- The ability to toggle individual listings on and off the map.
- Rental income and operating expense information.
- Estimated capitalization rates and cash flow projections.
- Side-by-side investment comparisons.
- Opportunities ranging from $650,000 to $1 million.
The goal was simple: give the investor the information and tools needed to compare opportunities intelligently.
Because buying investment property should never be a guessing game.
And I Found Some Interesting Opportunities
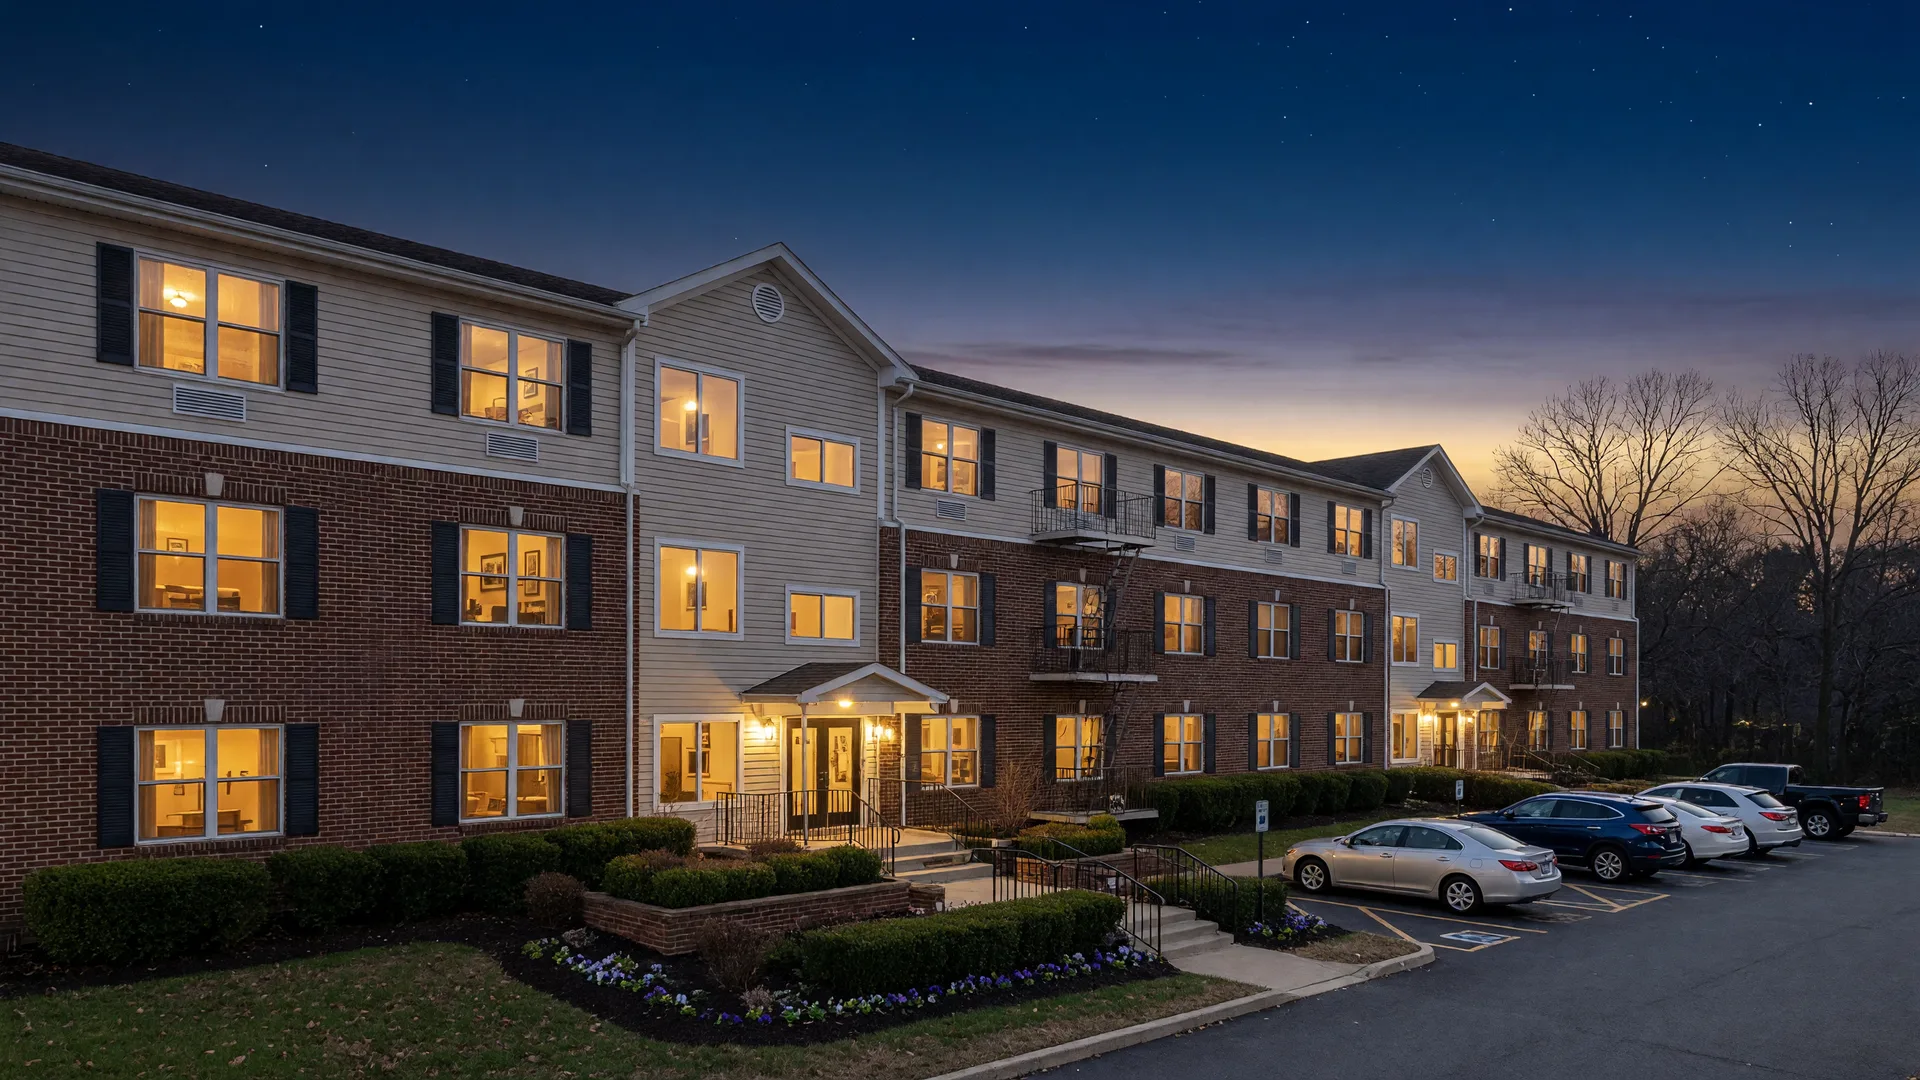
Among the properties we were evaluating were two multifamily investments.
One was a six-unit property built in 2008, priced at approximately $650,000.
The other was a six-unit, brand-new construction opportunity from 2026, priced at approximately $1 million.
The advertised and modeled investment returns were certainly worth investigating.
Then something unexpected happened.
The Plot Twist: The Investor Wanted Duplexes! 😂
After all the research, calculations, property comparisons, and the personalized website...
The investor began sending me duplexes to evaluate.
Now, there's absolutely nothing wrong with duplexes.
Some make excellent investments, and owning smaller residential properties may suit an investor's goals, financing preferences, or tolerance for risk.
But the best projected cap rate among the duplex opportunities we evaluated was approximately 6.8%.
One of those properties was built in 1965.
Compare that with the two multifamily opportunities, one built in 2008 and the other brand new.
That raised an interesting question.
What if we invested exactly the same amount of money in all three?
Not the same purchase price.
The same amount of the investor's own cash.
Let's Put $299,900 to Work
The duplex was priced at approximately $299,900.
So rather than comparing unequal purchase prices without context, I modeled investing that same $299,900 in each opportunity.
For the duplex, that meant purchasing outright.
For the multifamily investments, it meant using $299,900 as a down payment and financing the balance.
For the financed properties, the analysis assumes a 7.5% fixed interest rate amortized over 30 years.
Here's what the preliminary numbers showed.
Three opportunities. Same cash invested.
| Investment | Opportunity #1 | Opportunity #2 | Duplex |
|---|---|---|---|
| Property type | 6-unit multifamily | 6-unit multifamily | Duplex |
| Year built | 2008 | 2026 — new | 1965 |
| Purchase price | $650,000 | $1,000,000 | $299,900 |
| Cash invested | $299,900 | $299,900 | $299,900 |
| Amount financed | $350,100 | $700,100 | $0 |
| Estimated cap rate | 8.7% | 12.0%* | 6.8% |
| Annual NOI | $56,400 | $120,000* | $20,280 |
| Annual loan payments | ~$29,374 | ~$58,742 | $0 |
| Annual cash flow | ~$27,026 | ~$61,258 | $20,280 |
| Cash-on-cash return | 9.0% | 20.4% | 6.8% |
*These are preliminary, illustrative scenarios, not verified investment performance. The $1 million scenario assumes an actual 12% cap rate and $120,000 annual NOI, which must be confirmed. The modeled returns exclude closing costs, financing fees and additional reserves not already reflected in NOI. The 7.5% financing assumption is not a loan quote.
Now Look at the Difference!
Using the same $299,900 in cash:
The 1965 Duplex
Projected annual cash flow: $20,280
The 2008 Multifamily
Projected annual cash flow: $27,026
That's approximately $6,746 more per year than the duplex scenario.
The Brand-New 2026 Multifamily
Projected annual cash flow: $61,258, assuming the illustrative 12% cap-rate scenario is achieved.
That's approximately $40,978 more per year than the duplex scenario.
Same initial cash commitment.
Three different properties.
Three dramatically different projected outcomes.
Now that's worth sitting down and examining!
But before anyone rushes out to buy the property with the highest number, there's another side to this.
A Higher Return Doesn't Automatically Make It the Better Investment
This is where proper deal evaluation becomes critical.
A projected 20.4% cash-on-cash return certainly looks attractive on paper.
But what assumptions produced that figure?
Are the rents supported by actual signed leases?
Have all operating expenses been included?
What about vacancy, turnover, management, insurance, maintenance and capital expenditures?
How reliable are the income projections?
And what happens if the property doesn't perform as expected?
Financing also matters.
A higher loan balance can increase returns on invested cash when a property performs well, but it can also magnify losses and cash flow problems when income falls short.
An older duplex purchased entirely with cash might offer less income on paper while avoiding mortgage payments altogether.
That reduced debt exposure may be exactly what certain investors prefer.
The best investment isn't necessarily the one with the highest advertised return. It's the one whose verified numbers, risks and structure align with the investor's objectives.
That's the difference between finding property and evaluating investments.
Cap Rate and Cash-on-Cash Return Are Not the Same Thing
This is something I believe every investor should understand.
Cap Rate
Capitalization rate measures a property's annual net operating income relative to its purchase price, before financing.
Cap Rate = Annual NOI ÷ Purchase Price
Cash-on-Cash Return
Cash-on-cash return measures annual pre-tax cash flow after debt payments relative to the actual cash invested.
Cash-on-Cash Return = Annual Pre-Tax Cash Flow ÷ Total Cash Invested
That distinction matters enormously.
A property might have a respectable cap rate but produce disappointing cash-on-cash returns after mortgage payments.
Another might produce stronger leveraged returns, but with greater financial exposure.
It's why I prefer to analyze the entire investment rather than focus on a single headline percentage.
And Then I Got Fired! 😂
After identifying the opportunities, building the website, mapping the properties and running the numbers...
The relationship ended before we ever signed an agency agreement.
Such is life!
Buyers and sellers absolutely have the right to change direction, decide a relationship isn't the right fit, or work with someone else.
I respect that completely.
No hard feelings.
But here's something people outside the real estate industry don't always appreciate.
REALTORS® can invest considerable amounts of time, expertise and money without ever earning a single red cent.
We don't automatically get paid for researching properties.
Or preparing investment analyses.
Or spending hours evaluating potential deals.
Or building personalized technology.
Or the calls, emails, follow-ups and conversations behind the scenes.
In a typical commission-based arrangement, payment is contingent on the terms of the agreement and the transaction.
Not on how many hours we worked.
That's the business.
Three Lessons I Took Away
Lesson #1 — Deal evaluation is everything.
Never choose an investment simply because the price is lower, the building is newer, or the advertised yield looks impressive.
Understand the actual income, operating costs, debt, risks and return on invested capital.
Lesson #2 — My time is an investment too.
Perhaps I need to evaluate prospective clients as carefully as I evaluate the investment opportunities I identify! 😂
And fair enough. Relationships work best when both sides understand the expectations and value being delivered.
Lesson #3 — Opportunity deserves action.
After this experience, I realized something.
I'd already done the research.
I'd identified several promising investment possibilities.
I'd built the tools to help compare them.
So why stop now?
I need to get these opportunities in front of other serious investors — and quickly!
Not to create artificial urgency. Every property still needs proper verification, financing analysis and due diligence.
But opportunities worth investigating deserve attention while they're relevant and potentially available.
And that's exactly what I'm going to do.
Looking for Investment Property in Georgia?
Whether you're considering a duplex, a multifamily property, student housing, or another income-producing investment, my approach is straightforward.
We evaluate the deal before falling in love with the property.
I help investors review the available numbers, compare alternatives, understand the financing assumptions, and identify questions that need answering before making a decision.
Because the goal isn't simply to buy another property.
It's to make an informed investment decision.
And if you've got $200,000, $300,000, or $1 million to invest, understanding what that money can realistically achieve is well worth the conversation.
Interested in seeing how the numbers stack up?
Book a conversation with me at:
Or explore more about my approach at:
And if you've made it this far...
Yes, I've recovered from getting fired! 😂
Onwards and upwards.
Straight answers. Smart strategy. No mucking around.
Rob Dietrich | REALTOR®
eXp Realty | Georgia
Disclosure: Investment figures are illustrative projections based on stated assumptions, not guaranteed returns or verified current property performance. Actual financing, acquisition expenses, operating costs, occupancy, tax treatment and market conditions can materially affect results. Availability and investment details must be independently verified. This article is educational and is not individualized financial, tax or legal advice.
Written by
Rob Dietrich
Georgia REALTOR® with eXp Realty, AI Certified Real Estate Strategist, serving Gwinnett, Hall, Barrow and Jackson counties.
Read the full profile